Home Loan
What is a Home Loan?
A home loan is a secured loan you take to buy, build, or renovate a house. The property itself acts as collateral, so lenders check your income, credit score, and down-payment ability before approving. Home loans usually offer longer tenures and lower interest rates than unsecured loans, which makes EMIs easier to manage for big purchases.
At Mr. Loanwala, led by Tapan Agarwal (Registered DSA Loan Consultant), we make the journey of buying or building a home smoother, faster, and stress-free. As a trusted loan consultancy firm, we don’t just connect you with banks, we help you turn the dream of homeownership into reality with personalized guidance and a seamless loan experience.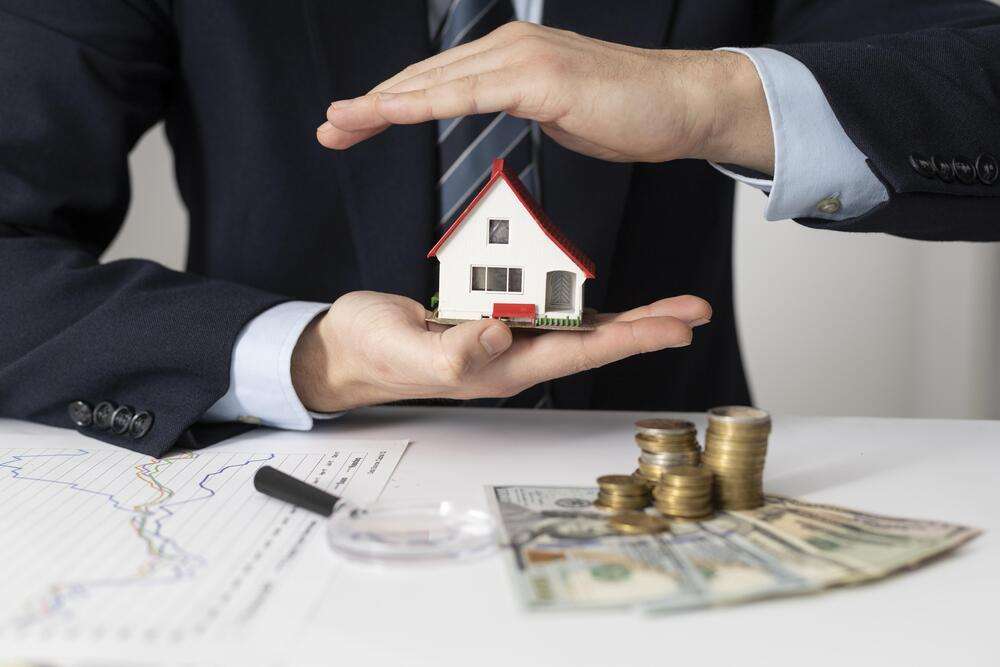
Features and Benefits of a Home Loan
A home loan is more than just financial support, it’s a practical way to turn your dream of owning a house into reality. Banks and NBFCs in India offer housing loans with flexible terms and borrower-friendly features that make home ownership easier.
- High Loan Amounts
Depending on eligibility and property value, lenders provide substantial loan amounts so you can finance a ready house, under-construction property, or even a plot. - Affordable Interest Rates
Home loans are secured against the property, so interest rates are generally lower compared to personal loans or credit cards. This makes repayment easier and cost-effective over the long term. - Flexible Repayment Tenure
Most lenders allow repayment periods ranging from 10 to 30 years. Longer tenure means smaller EMIs, while shorter tenure helps close the loan faster—borrowers can choose what works best. - Tax Benefits on Home Loans
Home loan repayment comes with income tax benefits under sections 80C and 24(b). Borrowers can save significantly on both principal and interest repayments, making the loan even more rewarding. - Balance Transfer Option
If another bank offers a lower interest rate, you can transfer your existing housing loan to save money. A home loan balance transfer helps reduce EMI burden and overall interest outgo. - Top-Up Facility
Many lenders allow you to borrow extra funds over your existing home loan. This top-up loan can be used for renovation, business, or personal expenses without needing a fresh loan application. - Improves Credit Profile
Timely repayment of a home loan builds a strong credit history. A good repayment record improves your CIBIL score and makes future borrowing easier. - Ownership and Asset Building
Repaying a home loan gradually builds equity in your property. Instead of paying rent, every EMI increases your share of ownership, turning your house into a long-term financial asset.
Home Loan EMI Calculator
How Mr. Loanwala Makes Home Loans Easy
At Mr. Loanwala, we make the home loan process simpler, faster, and less stressful. From comparing interest rates across leading banks to guiding you with eligibility checks, paperwork, and approvals, our team ensures you get the best deal for your housing needs. Whether you’re buying your first home, investing in a second property, or transferring an existing loan for lower EMIs, we provide step-by-step support so you don’t have to worry about complicated formalities. With our experience and trusted lender network, getting a home loan becomes a smooth journey instead of a confusing task.
Frequently Asked Questions
Home loan process is straightforward:
- Apply with income proof, property documents, and ID
- Bank verifies your eligibility and property value
- Loan is sanctioned (usually 75-90% of property value)
- Amount is disbursed directly to the seller or builder
- You repay through monthly EMIs over 10-30 years
- Property remains mortgaged until full repayment
Mr. Loanwala assists you throughout this journey with expert guidance.
Home loan EMI is calculated using this formula:
EMI = [P x R x (1+R)^N] / [(1+R)^N-1]
Where:
- P = Loan amount
- R = Monthly interest rate (annual rate ÷ 12 months)
- N = Loan tenure in months
Your EMI includes both principal and interest. In early years, you pay more interest; later, more principal gets repaid.
Home loan interest is calculated on the reducing balance method:
- Interest is charged only on the outstanding loan amount
- As you repay EMIs, the principal reduces and so does the interest
- Each EMI has two parts: principal + interest
- Over time, the interest portion decreases and principal portion increases
This method is more beneficial than flat rate calculation.
Yes, home loan tenure can be reduced in two ways:
- Partial prepayment: Pay lump sum amounts to reduce outstanding balance
- Increase EMI amount: Request your bank to shorten the tenure with higher EMIs
Reducing tenure helps you save significantly on total interest paid. Check with your lender about prepayment charges, if any.
Yes, but with conditions. Most banks offer land purchase loans or plot loans, but:
- The land must be in approved residential/commercial areas
- Clear titles and legal documents are mandatory
- Loan amount is typically lower (60-70% of land value)
- Interest rates may be slightly higher than regular home loans
- Some banks require construction commitment within a timeframe
We can help you find lenders offering competitive land loan options.
Yes, home loans can be transferred through balance transfer or loan takeover:
- Transfer your loan from one bank to another offering better rates
- Useful when you find lower interest rates or better terms
- You'll need to pay processing fees and legal charges for the transfer
- The new bank reassesses your eligibility and property
Mr. Loanwala can help you evaluate if transferring your home loan will save you money in the long run.
The best home loan depends on your individual needs and financial situation. Key factors to consider include:
- Interest rates (compare fixed vs. floating rates)
- Processing fees and charges
- Loan tenure flexibility
- Prepayment and foreclosure terms
- Customer service and approval speed
At Mr. Loanwala, we help you compare options from multiple banks and find the loan that best matches your requirements and budget.